Start with obligations, then map the dependencies
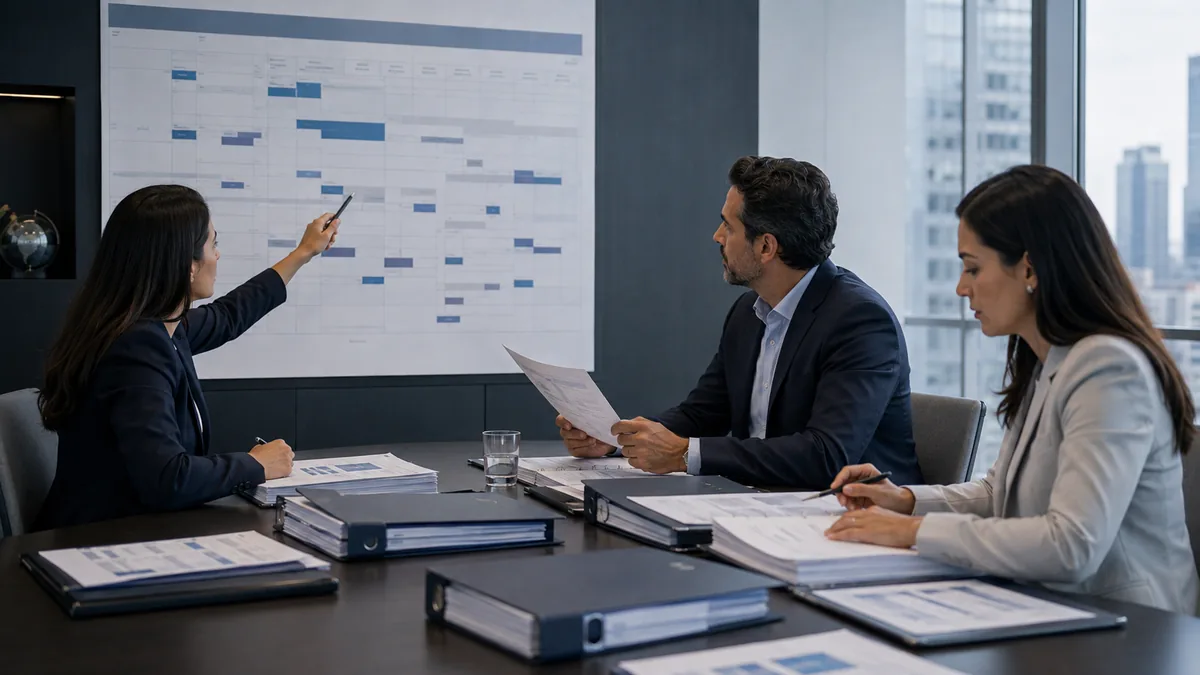
A regional tax calendar usually begins as a list of filing and payment dates. That is necessary, but it does not tell the finance team whether the obligation is actually under control. For each recurring item, add the information deadline, responsible internal owner, local adviser, review point and any accounting dependency that must be complete first.
This turns the calendar from a reminder tool into a coordination tool.
Use one regional taxonomy for obligations
Countries use different terminology, forms and tax mechanics. The regional view still benefits from broad categories such as corporate income tax, indirect tax, withholding, transfer-pricing deliverables and information returns. The local team can preserve the exact legal name and technical detail while Group Finance receives a consistent portfolio view.
The taxonomy should help management group work, not replace local technical advice.
- Obligation and jurisdiction.
- Statutory due date and internal target date.
- Data owner and local professional contact.
- Required accounting schedules or source data.
- Status, open issue and escalation owner.
Move the internal deadline ahead of the statutory deadline
If the first management alert occurs on the legal due date, there is no coordination buffer. Set an internal date for data readiness and another for adviser review. The gap does not need to be the same in every country; it should reflect the complexity of the obligation and how much information depends on close.
For recurring items, the calendar should show whether data is complete, not merely whether someone has started the work.
Connect the calendar to month-end close
Many tax deliverables depend on reconciled revenue, payroll, intercompany balances, withholding information or supporting schedules. If the accounting close and tax calendar operate independently, the same data problems appear repeatedly at the last minute.
Regional Finance should identify which tax obligations depend on which close outputs and make those handoffs explicit.
Escalate issues, not every status update
A regional CFO does not need a daily list of all filings. The management view should highlight missed internal dates, missing source data, unresolved technical questions, adviser delays and obligations that may require a decision from headquarters.
Routine compliance can remain routine. The calendar earns its value when it makes the exceptions visible early.
Keep execution responsibility jurisdiction-specific
A regional calendar creates oversight; it does not make local filing responsibility universal. The firm or professional responsible for technical analysis and submission should be confirmed for each jurisdiction and engagement. That distinction should be visible in the calendar itself.
This prevents a regional coordination process from blurring local professional responsibilities.
Design the calendar around cadence, not only annual deadlines
Some obligations recur monthly, others quarterly or annually, and some are triggered by transactions or corporate events. The regional calendar should make those cadences visible so recurring work can be planned around close rather than rediscovered each cycle. It is especially helpful to separate high-frequency obligations from annual items that require longer lead times and more documentation.
For each category, note the earliest dependency. If a quarterly return depends on reconciled revenue and intercompany data, the internal work should begin with those accounting outputs, not with the filing date itself.
Build change control into the calendar
Local tax rules, forms and deadlines can change. The regional team therefore needs a clear owner for maintaining each jurisdiction’s calendar and a way to record when a date or requirement has been updated. That responsibility may sit with the in-country adviser, local finance or another professional team depending on the engagement.
The regional layer should not independently interpret local law when that is outside its role. Its job is to make sure changes identified by the responsible local professional are reflected in the operating calendar and communicated to the teams that need to provide data or approvals.
Multi-Country Tax Compliance Coordination
Coordinate calendars, data and responsibilities across jurisdictions.
Explore the related service →